
Running a small business means making money decisions every week, usually on your own and usually in a hurry. And most financial advice for small business owners arrives as a list: eight tips, ten tips, a checklist you skim on your phone and forget by lunch.
The trouble with lists is that they treat every tip as equal. In practice a couple of decisions do most of the damage, or most of the good: how you pay yourself, and whether you understand the gap between profit and cash. Get those right and the rest of your business finances get much easier to manage.
The figures business owners need to know:
- Personal Allowance: currently £12,570, with basic-rate income tax at 20% up to £50,270
- Dividend tax: currently 10.75% at the basic rate and 35.75% at the higher rate, after a £500 dividend allowance
- Employer National Insurance: currently 15% on pay above £5,000 a year, offset by an Employment Allowance of up to £10,500
- Making Tax Digital for Income Tax: currently applies to sole traders and landlords with qualifying income over £50,000
- National Living Wage: currently £12.71 an hour for workers aged 21 and over
None of those numbers is dramatic on its own. Together they change how you should pay yourself and keep on top of your books, and plenty of owners haven’t noticed.
Financial planning starts with paying yourself
Here’s the habit I’d break first. A business owner who pours every spare pound back into the business and takes nothing out feels virtuous, but it’s usually where the trouble starts. Personal costs land on the business card, and two sets of money that HMRC expects you to keep apart get blurred.
Keep separate accounts. Pay yourself on a schedule, even a modest amount, and move money across on purpose rather than whenever the fridge is empty.
How you do it depends on how you trade. If you’re a sole trader, move a fixed slice of every payment into a separate tax pot the day it lands, ready for your personal tax bill. Around a quarter is a sensible starting point, but your accountant should set the real figure from your profits.
If you run a limited company, the usual approach is a small salary topped up with dividends. It still works, but dividend tax, employer National Insurance and the Employment Allowance have all moved in recent years. The allowance can now absorb the employer NI on a director’s salary, as long as at least one other employee is also paid above the £5,000 threshold. If the director is the only person whose pay triggers employer NI, the company can’t claim it. The salary that suited the old rates may not suit the current ones, so re-run your remuneration every April against the optimal director salary and dividend split for the year.
Cash flow isn’t profit, and the gap sinks businesses
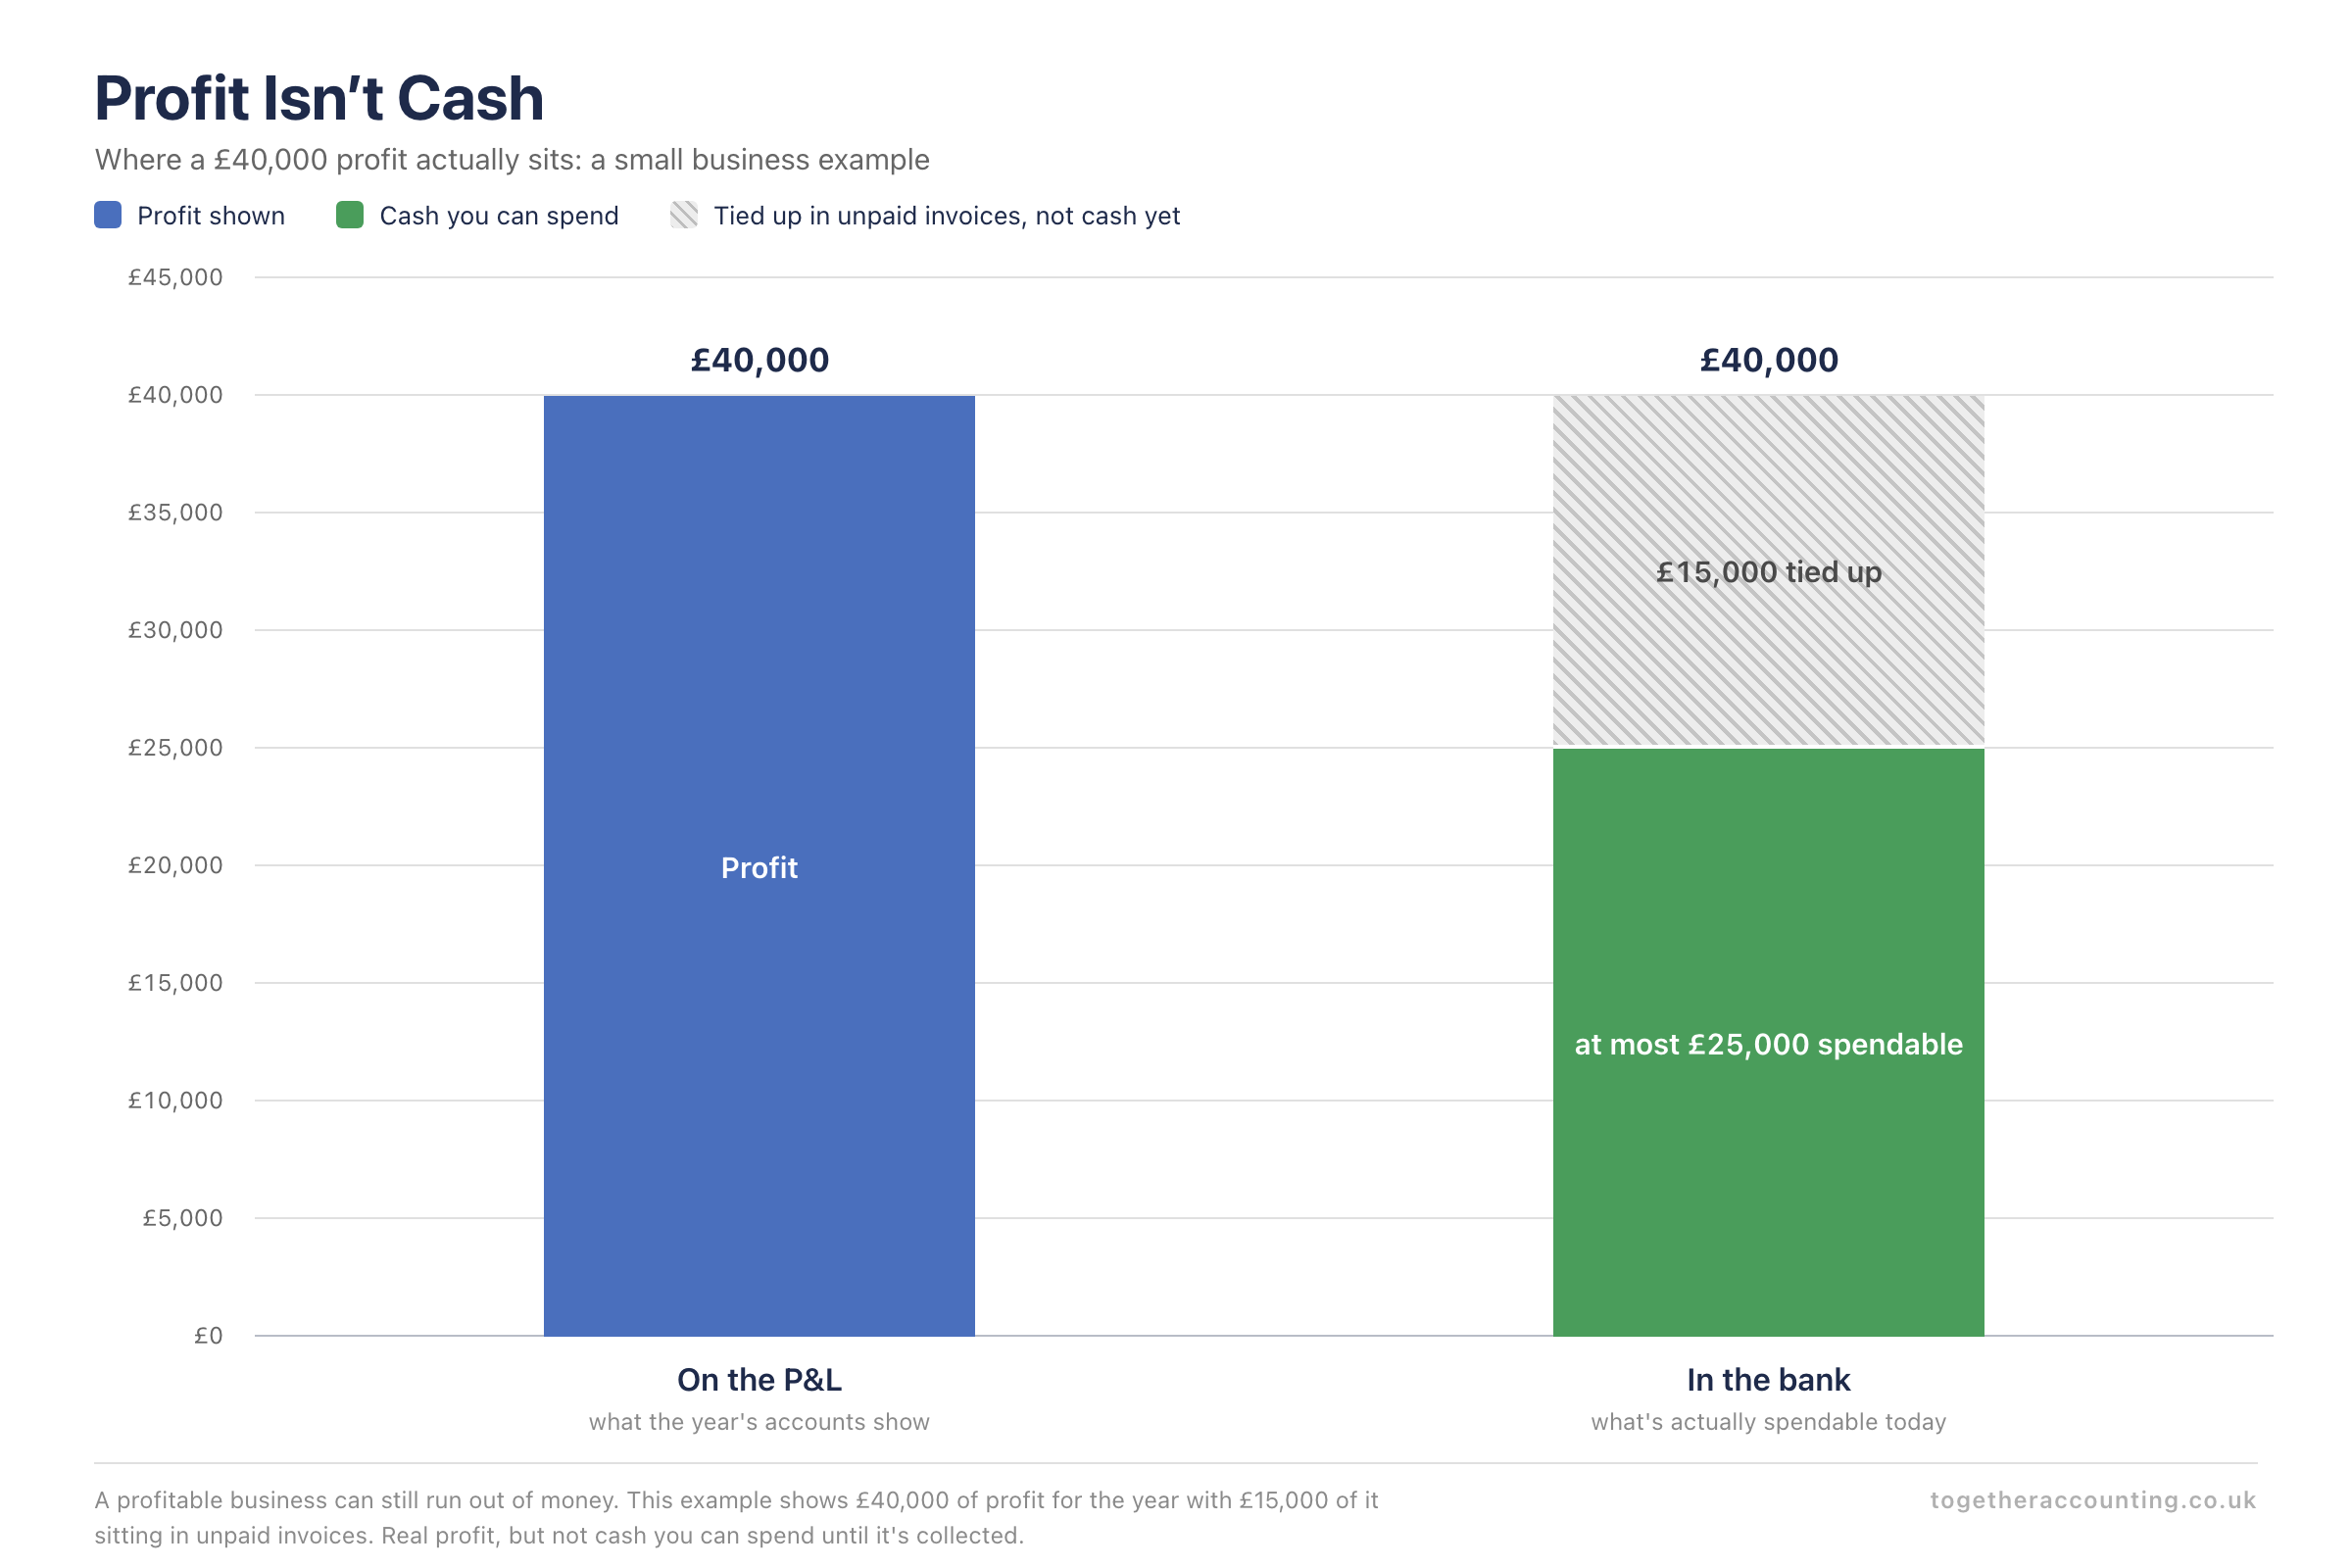
A profitable business can still run out of money. Your profit and loss account might show £40,000 of profit for the year, but if £15,000 of that is sitting in unpaid invoices and another chunk went on stock you haven’t sold, your bank balance tells a very different story. Left unmanaged, that gap between profit and cash is how otherwise healthy businesses slide towards insolvency.
Profit is what you’ve earned on paper. Cash flow is the money that actually moves through your account, and when. Wages, VAT and corporation tax all come out of the second one.
Running a business on the profit figure alone is like driving at night with only the rear-view mirror. You can see exactly where you’ve been.
The fix is a simple financial tool: a rolling 13-week cash flow forecast, essentially a short-term budget for your bank account. List your income and outgoings for each week for the next three months, update it every Friday, and roll it forward a week. Once it’s set up it takes half an hour a week, and it shows you a shortfall weeks before it arrives, while you still have choices.
Seasonal businesses need this more than anyone. A garden centre or a holiday-let cleaning firm on the Norfolk coast can have a brilliant summer and a frightening February, and the forecast is what tells you to hold cash back in August. If you’d like hands-on help with your cash flow forecasting, that’s part of what our management accounts service covers.
Unpaid invoices and late payment
Late payment is the cash problem we see most often, and it’s rarely bad luck. Usually the invoice went out late, the terms were vague, or nobody chased it until it was two months overdue.
Four changes make a real difference:
- Invoice the day the work is finished, not at the end of the month.
- Take a deposit up front on larger jobs.
- Set automated reminders for just before and just after the due date.
- Put your bank details and a payment link on every invoice.
Worked Example: Take a small Norwich design agency owed £15,000 across six overdue invoices. On paper it’s a profitable business. In practice it can’t cover next month’s payroll without its overdraft, and a 13-week forecast shows exactly which week the gap arrives. Moving new projects to a 50% deposit, invoicing on completion and switching on automated reminders means the next £15,000 doesn’t pile up the same way, and the overdraft goes back to being a safety net rather than a lifeline.
Business loans and funding: borrow for a reason
Debt isn’t a dirty word. Borrowing to buy a van that earns its keep is sensible. Borrowing to cover wages because customers are paying late is a warning sign, and a loan only delays the conversation you need to have with those customers.
| Funding option | How it works | Best suited to |
|---|---|---|
| Overdraft or revolving credit | Draw and repay as needed, paying interest only on what you use | Short-term working capital gaps between paying out and getting paid |
| Term loan | A lump sum repaid in fixed instalments | One-off investments such as a fit-out or expansion |
| Asset finance | The cost of equipment spread over several years, secured on the asset | Vehicles, machinery and kit that pays for itself |
| Trade credit | Suppliers let you pay after delivery | Stock-heavy businesses such as shops and online sellers |
| Government-backed loans and grants | Funding on favourable terms, such as Start Up Loans, usually with conditions attached | Start-ups and business growth or innovation projects |
The rule I’d stick to, whether you’re a startup or ten years in: match the length of the funding to the life of the thing you’re buying. That’s risk management, not caution for its own sake. A five-year loan to plug a three-month gap is expensive. An overdraft to buy a vehicle is risky.
Any lender will check your business credit file, which reflects whether you pay on time, file your accounts promptly and have any county court judgments against you. Each credit reference agency uses its own scale, so there’s no magic number to chase. Chase the habits instead.
Records, controls and the compliance you can’t skip
Good bookkeeping used to be about making year-end less painful. Now it’s a legal requirement for far more small businesses.
Making Tax Digital for Income Tax applies to sole traders and landlords whose qualifying income, meaning turnover before expenses, is over £50,000. That means keeping digital records and sending quarterly updates to HMRC through compatible software. The threshold drops to £30,000 from April 2027 and £20,000 from April 2028, so many more people will be pulled in soon. Our guide to Making Tax Digital for Income Tax covers what to do before it applies to you.
Picture a Norwich tradesperson turning over £58,000 on paper records. MTD moves them onto software, like it or not. The upside? Quarterly updates show a seasonal dip months earlier than a once-a-year tax return ever did.
Company directors have their own new job. Identity verification at Companies House is now mandatory for directors and people with significant control, and each existing company’s deadline is tied to its next confirmation statement. An unverified director can hold up that filing, so don’t leave it to the last week. See our guide to Companies House identity verification for how it works.
Inside the business, simple controls stop small errors becoming expensive ones. Have a second person approve payments, reconcile the bank weekly and review your profit and loss each month. It feels like admin. It’s also how you catch a supplier billing you twice.
Do small business owners need a financial adviser?
Good financial advice for small business owners usually starts with an accountant, not a financial adviser. The two do different jobs. Your accountant keeps the business compliant, prepares your tax returns and should tell you what your numbers actually say. An independent financial adviser looks after personal wealth, such as pensions, investments and share schemes.
My honest view? If your accountant only appears once a year to file your accounts, you’re paying for compliance, not financial management. The value sits in the conversations in between, about remuneration, cash flow, and whether the next hire is affordable once wages, employer NI and pension costs are added up, as set out in our guide to the true cost of employing someone. Once personal wealth builds and your financial goals reach beyond the business, a financial adviser earns their fee alongside us.
Free financial advice for small business owners in Norwich and Norfolk
If you’re running a small business in Norwich or anywhere else in Norfolk, you don’t have to pay for every piece of advice. The New Anglia Growth Hub offers free business support and signposts funding sources, including grant schemes for growth and equipment. It’s a good first call before you walk into a bank.
What free advice can’t do is sit down with your own numbers and tell you the right salary for your company this year, whether your forecast holds up, or what it means for your financial future. That’s the gap between general financial advice for small business owners and advice about your business. It’s the work we do every week for sole traders, limited companies and landlords across Norfolk.
FAQ
What is the best advice for small business owners?
Check your cash position every week rather than your profit once a year. Pay yourself on a schedule, keep business and personal money apart, and put tax aside as you earn.
Do I need a financial advisor for my small business?
Most small businesses need an accountant first. An accountant handles tax, compliance and business planning, while a financial adviser looks after personal investments and pensions. As your wealth grows, it’s often worth having both.
Where can I get free advice for my small business in the UK?
Your local growth hub is the best starting point, and in Norfolk that’s the New Anglia Growth Hub. GOV.UK also publishes free guidance on tax, employing staff and Making Tax Digital.
What’s the difference between profit and cash flow?
Profit is income minus expenses over a period, on paper. Cash flow is the money actually moving through your bank account, and when. You can be profitable and still run short if customers pay late.
If you’d like someone to look at your business finances properly, we’re here to help.
This article provides general guidance based on current legislation. Tax and employment law are complex and fact-specific. The information here should not be relied upon as advice for your particular circumstances. Please consult a qualified accountant or professional advisor for guidance tailored to your situation.
