
If you own a trading business, you’ve probably heard that inheritance tax relief on it has been cut, and you may have been planning around a £1 million figure ever since. That number is out of date. Business property relief currently gives 100% relief on the first £2.5 million of qualifying business and agricultural property, and 50% relief on anything above it.
The new rules started on 6 April 2026. For many business owners, the bigger risk now is making decisions based on the old cap.
The headline numbers:
Relief on the first £2.5m of combined agricultural and business property
Relief above that, which means an effective inheritance tax rate of 20% on the excess
The most a couple can currently shelter, once any unused allowance passes to the surviving spouse or civil partner
Flat relief on shares on AIM and other “not listed” markets, whatever the holding is worth
How did so many people end up with the wrong figure? The government announced a £1m cap at the Autumn Budget on 30 October 2024. It later made the allowance transferable between spouses, then on 23 December 2025 raised it to £2.5m.
The final rules went into Finance Act 2026, which received Royal Assent on 18 March 2026. An older GOV.UK policy paper still quotes £1m, and so did the first version of this article. That’s why we’ve rewritten it.
| 30 October 2024 |
Autumn Budget: £1m cap announced The government announces a £1m cap on 100% relief for business and agricultural property. |
|
| 23 December 2025 |
Cap raised to £2.5m The allowance rises to £2.5m, on top of having already been made transferable between spouses and civil partners. |
|
| 18 March 2026 |
Finance Act 2026 receives Royal Assent The final rules are set in law. |
|
| 6 April 2026 |
New rules take effect The £2.5m cap, spousal transfer and flat 50% AIM relief all start applying. |
What is business property relief and how does BPR work?
Business property relief (BPR), often shortened to business relief or IHT business relief, reduces the taxable value on the transfer of qualifying business property. It applies when those assets pass on death, and to some lifetime gifts. The rules sit in the Inheritance Tax Act 1984, sections 103 to 114.
The mechanics are simple enough. HMRC takes the value of the asset, applies the rate of relief, and only taxes what’s left. At 100% relief, the business drops out of the IHT calculation completely. At 50%, half its value stays in. Either way, it’s the value of a business, or other qualifying business assets, that’s assessed for IHT, not the profit it makes in a year.
Who qualifies for business property relief?
To qualify for business relief, the business asset has to be relevant business property. In practice, these types of business assets usually qualify for relief:
- a business, or an interest in a business, such as a sole trade or a share in a partnership
- unquoted shares in a trading company
- land, buildings or machinery used in a qualifying business
Two tests then decide whether relief is available. First, you normally need to have owned the asset for at least two years. Second, the business must be trading. A business that consists wholly or mainly of making or holding investments doesn’t qualify for relief, however hard the owner works at it.
That second test catches more people than you’d think. We regularly meet landlords who see their portfolio as a proper business, and in every practical sense it is one. For IHT purposes, though, a lettings business is usually treated as holding investments, so it falls outside BPR altogether. It’s a separate conversation, best had as part of your landlord tax planning.
What changed on 6 April 2026
Here’s the before and after for the assets qualifying for relief.
| Category | Before 6 April 2026 | From 6 April 2026 |
|---|---|---|
| Qualifying business and agricultural property | 100% relief, no cap | 100% on the first £2.5m combined, 50% above |
| Unused allowance on first death | No allowance to pass on | Transfers to a surviving spouse or civil partner |
| AIM and other “not listed” shares | 100% relief after two years’ ownership | 50% relief in all cases |
| Business and agricultural property in trusts | 100% relief, no cap | £2.5m allowance applies |
The word that matters in the first row is “combined”. One £2.5m allowance covers agricultural property relief, often just called agricultural relief, and BPR together, so a family with farmland and a trading company shares a single allowance across both.
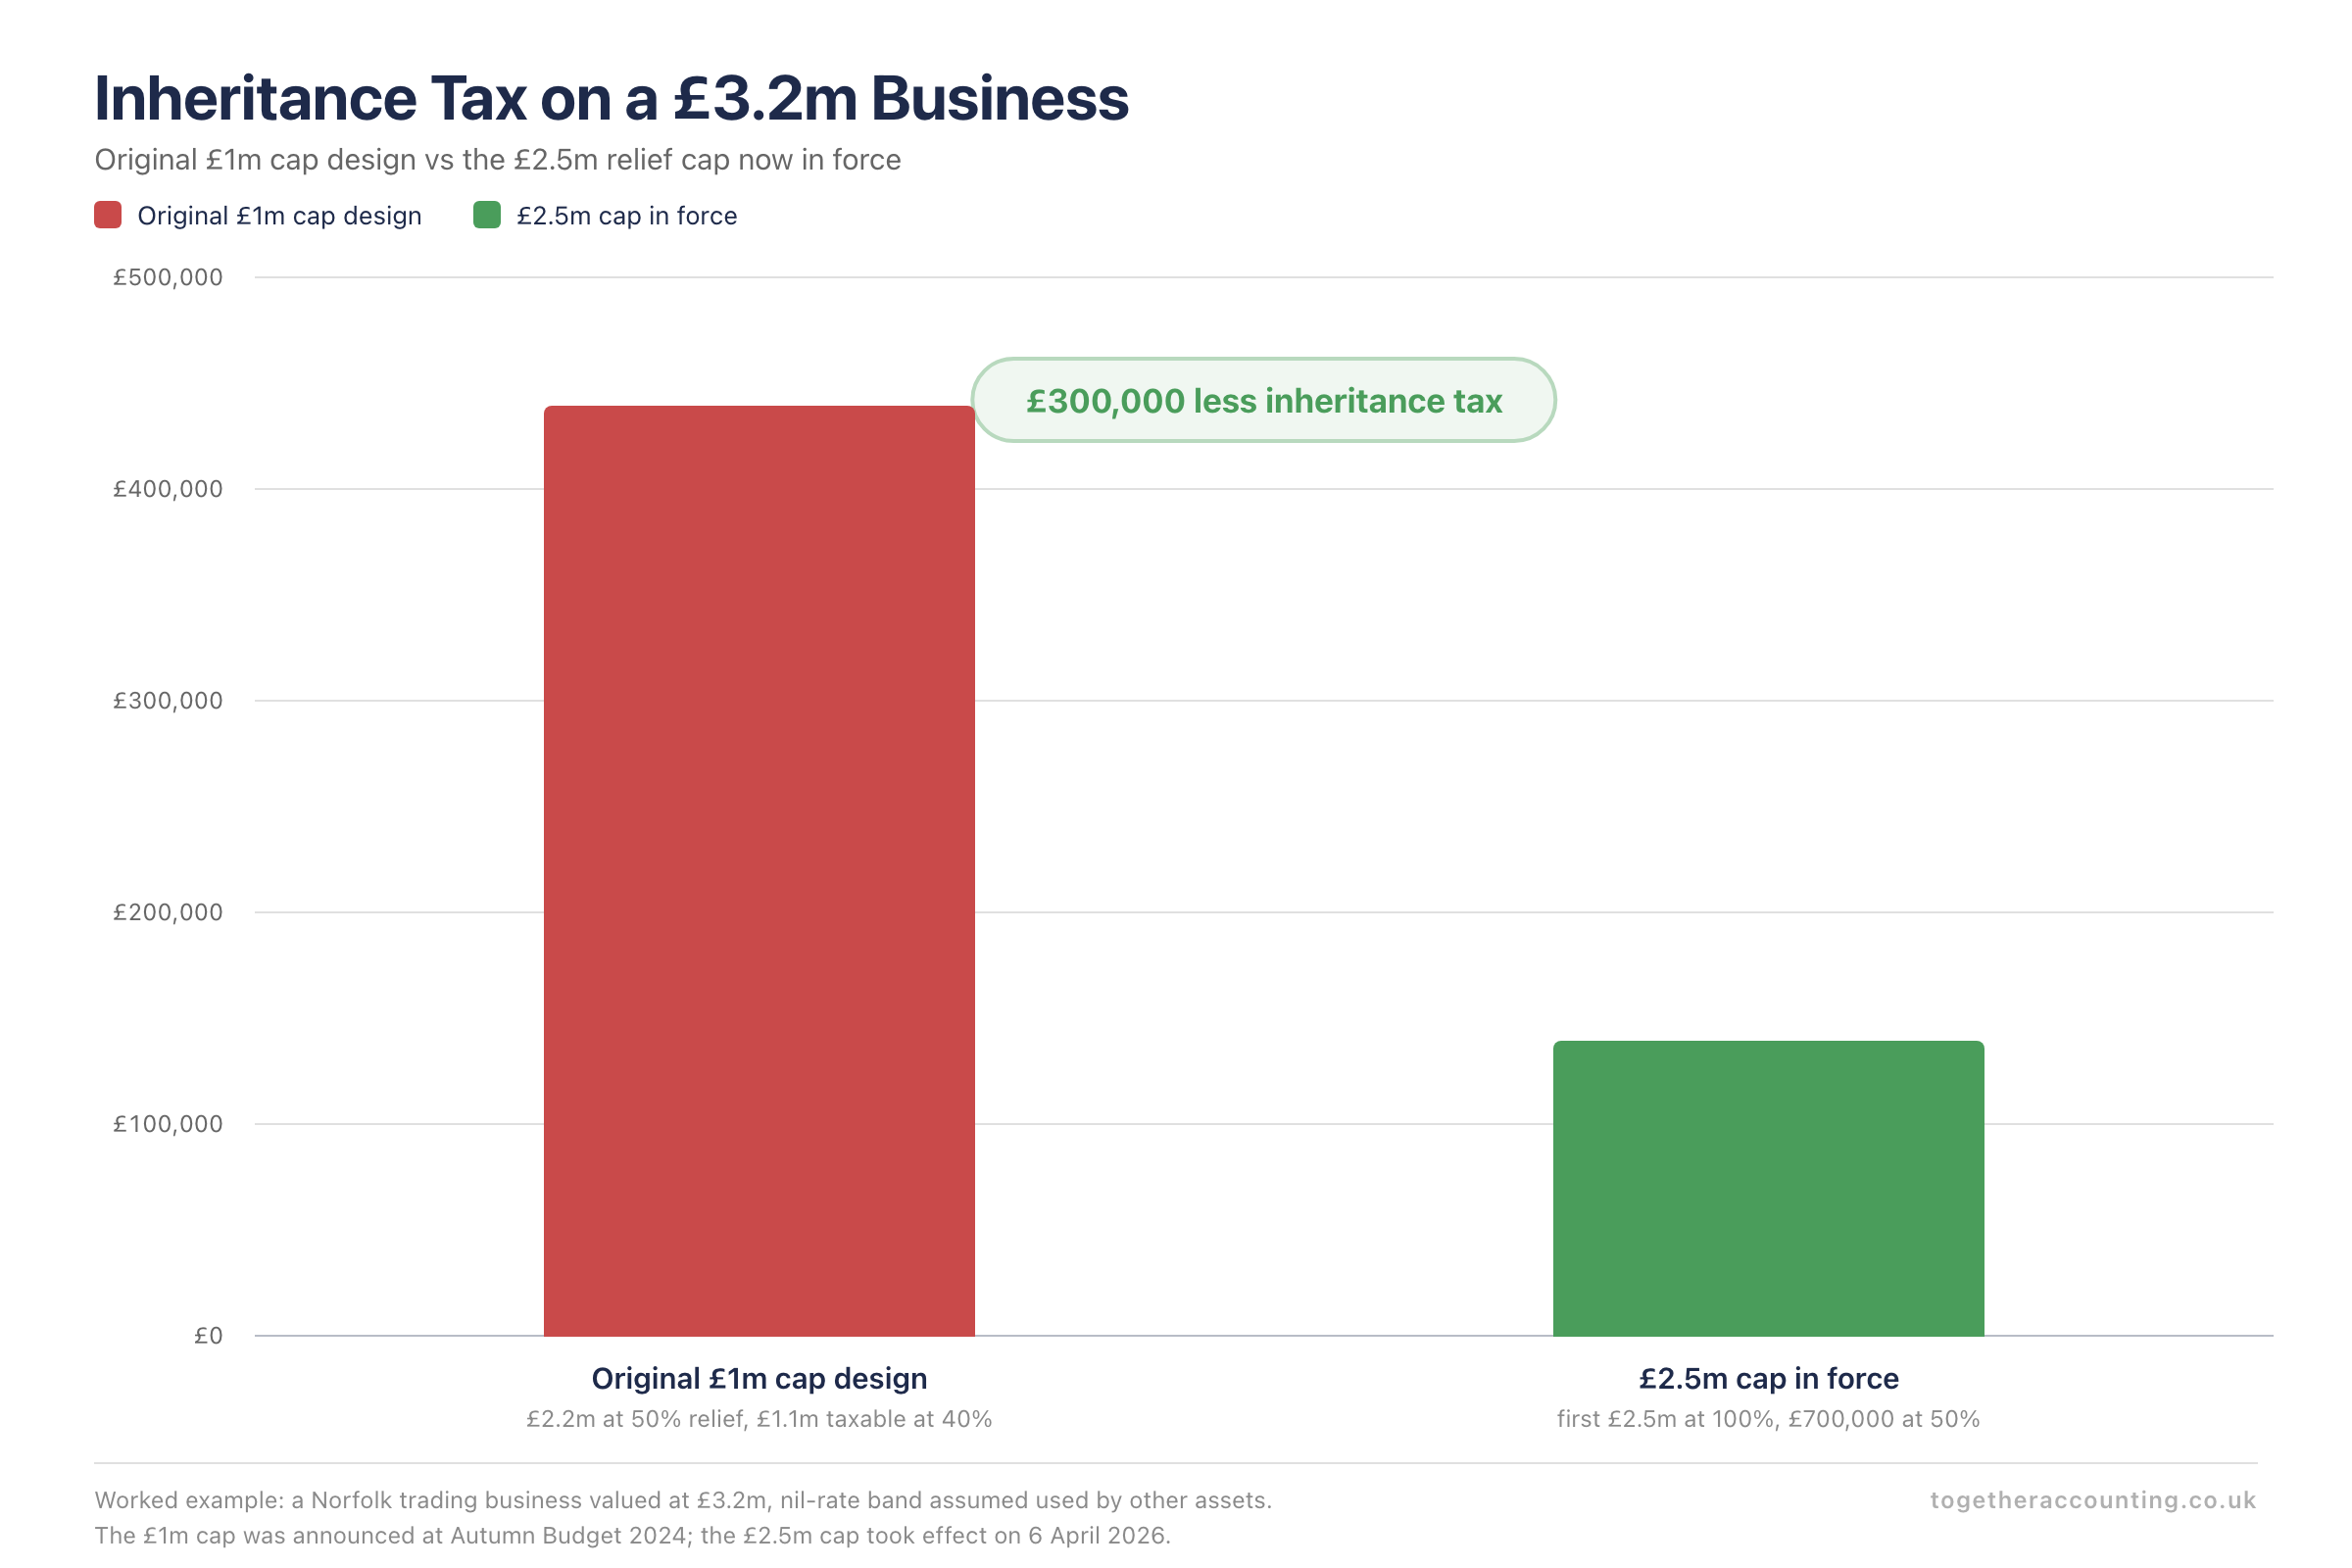
Worked Example: Take a Norfolk engineering firm owned outright by one director and valued at £3.2m. Assume the nil-rate band is already used by other assets.
- Under the original £1m design: £2.2m would get only 50% relief, leaving £1.1m taxable at 40% = £440,000
- Under the rules in force: the first £2.5m gets 100% relief, and the remaining £700,000 gets 50%
- Taxable value: £350,000 at 40% = £140,000
Inheritance tax on a £3.2m trading business
Original £1m cap design
£440,000
£2.2m at 50% relief, £1.1m taxable at 40%
£2.5m cap in force
£140,000
First £2.5m at 100%, £700,000 at 50%, £350,000 taxable at 40%
A £300,000 difference on one business. Together Accounting worked example, Norfolk engineering firm valued at £3.2m, nil-rate band assumed used by other assets.
If the director spent 2025 restructuring around the lower figure, some of that work may now be unnecessary. Some of it may even be working against them.
AIM shares: the change most owners are missing
This is the one we’d put at the top of any review. For years, buying shares on the Alternative Investment Market (AIM) was a standard way to reduce IHT, because after two years they qualified for 100% relief. That’s gone. Shares on markets designated as “not listed”, which includes AIM, now get 50% relief in every case. They don’t use the £2.5m allowance at all.
Consider a business owner with a £1.8m estate, £400,000 of it in AIM shares bought purely for IHT planning. Their total qualifying property sits well under £2.5m, so they might assume they’re fine. They aren’t. Half the AIM holding, £200,000, is now exposed, which could add £80,000 to their IHT liability if the nil-rate band is used elsewhere.
AIM and other “not listed” shares: the relief cut
Before
100%
after 2 years’ ownership
Now
50%
flat, in all cases
Before
£0
fully sheltered
Now
£200,000
could mean an £80,000 bill
AIM and other “not listed” shares no longer use the £2.5m allowance at all – they get a flat 50% relief regardless of holding size. Source: gov.uk agricultural property relief and business property relief changes.
AIM holdings need their own conversation, separate from the rest of your planning. For some owners, keeping value inside their own trading company now does a better job than an AIM portfolio.
Couples and the transferable allowance
Transferability is good news, but it doesn’t look after itself. Picture a married couple with £4.5m of combined business and agricultural assets. Within the £5m joint ceiling, they can currently shelter the lot at 100% relief, provided the first spouse to die leaves their unused allowance to the survivor. That makes wills and succession planning worth revisiting together. Business succession plans often hinge on how much of that relief survives to the next generation, so it pays to check both together.
How the £5m couple ceiling covers a £4.5m estate
| Qualifying assets 90% |
Combined business and agricultural assets £4.5m |
Headroom to the £5m ceiling £0.5m |
£4.5m is 90% of the £5m joint ceiling a couple can currently shelter at 100% relief, provided the first spouse to die leaves their unused allowance to the survivor. Source: Together Accounting worked example.
The catch is paperwork. Many wills were drafted around the original, non-transferable £1m design. If yours was, get it checked against the rules that actually apply.
Trusts and the ten-year anniversary
Trusts get the same £2.5m allowance for relievable business and agricultural property. For a trust set up before 30 October 2024, the new rules bite from its next ten-year anniversary on or after 6 April 2026. Trustees should know exactly when that date falls, because it drives the periodic charge calculation on that trust property.
What to do now
Most of this is fixable, and none of it needs a panic.
- Re-run your estate numbers against £2.5m, not £1m. Plenty of owners who expected to be caught are now comfortably under the cap, or under £5m as a couple. Find out whether you qualify and where you actually sit.
- Review your wills together. If they predate the transferable allowance, make sure the unused allowance can pass to the survivor.
- Look at AIM holdings on their own. Work out what the flat 50% relief means for each holding and whether another structure would suit you better.
- Protect your trading status. Keep records showing how assets are used for business purposes, and watch for investment activity creeping into a trading company.
- Plan for any excess. If your qualifying assets are still likely to exceed the allowance, life cover written into trust is a common way to fund the IHT bill on the excess.
- Trustees, diary the next ten-year anniversary. That’s when the allowance starts to apply to older trusts.
FAQs
What is the threshold for 100% business property relief?
Currently, 100% relief from IHT applies to the first £2.5m of combined agricultural and business property. Anything above that gets 50% relief. Unused allowance can transfer to a surviving spouse or civil partner, so a couple can shelter up to £5m.
Who qualifies for small business relief?
People often mix up two different reliefs. Small business rate relief cuts business rates on premises, while business property relief cuts inheritance tax on business assets. To qualify for BPR, you generally need a trading business, or shares or assets used in one, owned for at least two years.
What are the changes to business property relief under the IHT rules?
From 6 April 2026, 100% relief is capped at £2.5m of combined business and agricultural property, with 50% relief above. The allowance transfers between spouses, AIM shares get a flat 50%, and the £2.5m allowance also applies to business and agricultural property held in trusts.
Does a property lettings business qualify for business property relief?
Usually not. A business that’s wholly or mainly holding investments is excluded, and letting property normally counts as an investment activity. There are narrow exceptions where substantial services go alongside the letting, and those need individual advice.
We’d much rather have this conversation now than after a death, when the options narrow fast. If you’d like us to look at your business and estate as part of wider estate planning, our inheritance tax planning service can walk through the detail with you.
This article provides general guidance based on current legislation. Tax law is complex and fact-specific. The information here should not be relied upon as advice for your particular circumstances. Please consult a qualified accountant or professional advisor for guidance tailored to your situation.
