
Updated for the 2026/27 tax year.
Ask a room full of business owners which UK tax bracket they’re in and half will get it wrong. The figures below cover the 2026/27 tax year, which runs from 6 April 2026 to 5 April 2027, and the Personal Allowance, basic rate limit and higher rate threshold in them are frozen until April 2031 in England, Wales and Northern Ireland (Scottish bands are set by Holyrood).
That freeze is the whole story. Pay rises keep coming and the bands don’t move, so as pay rises more people are pulled into higher rates while the bands stay fixed.
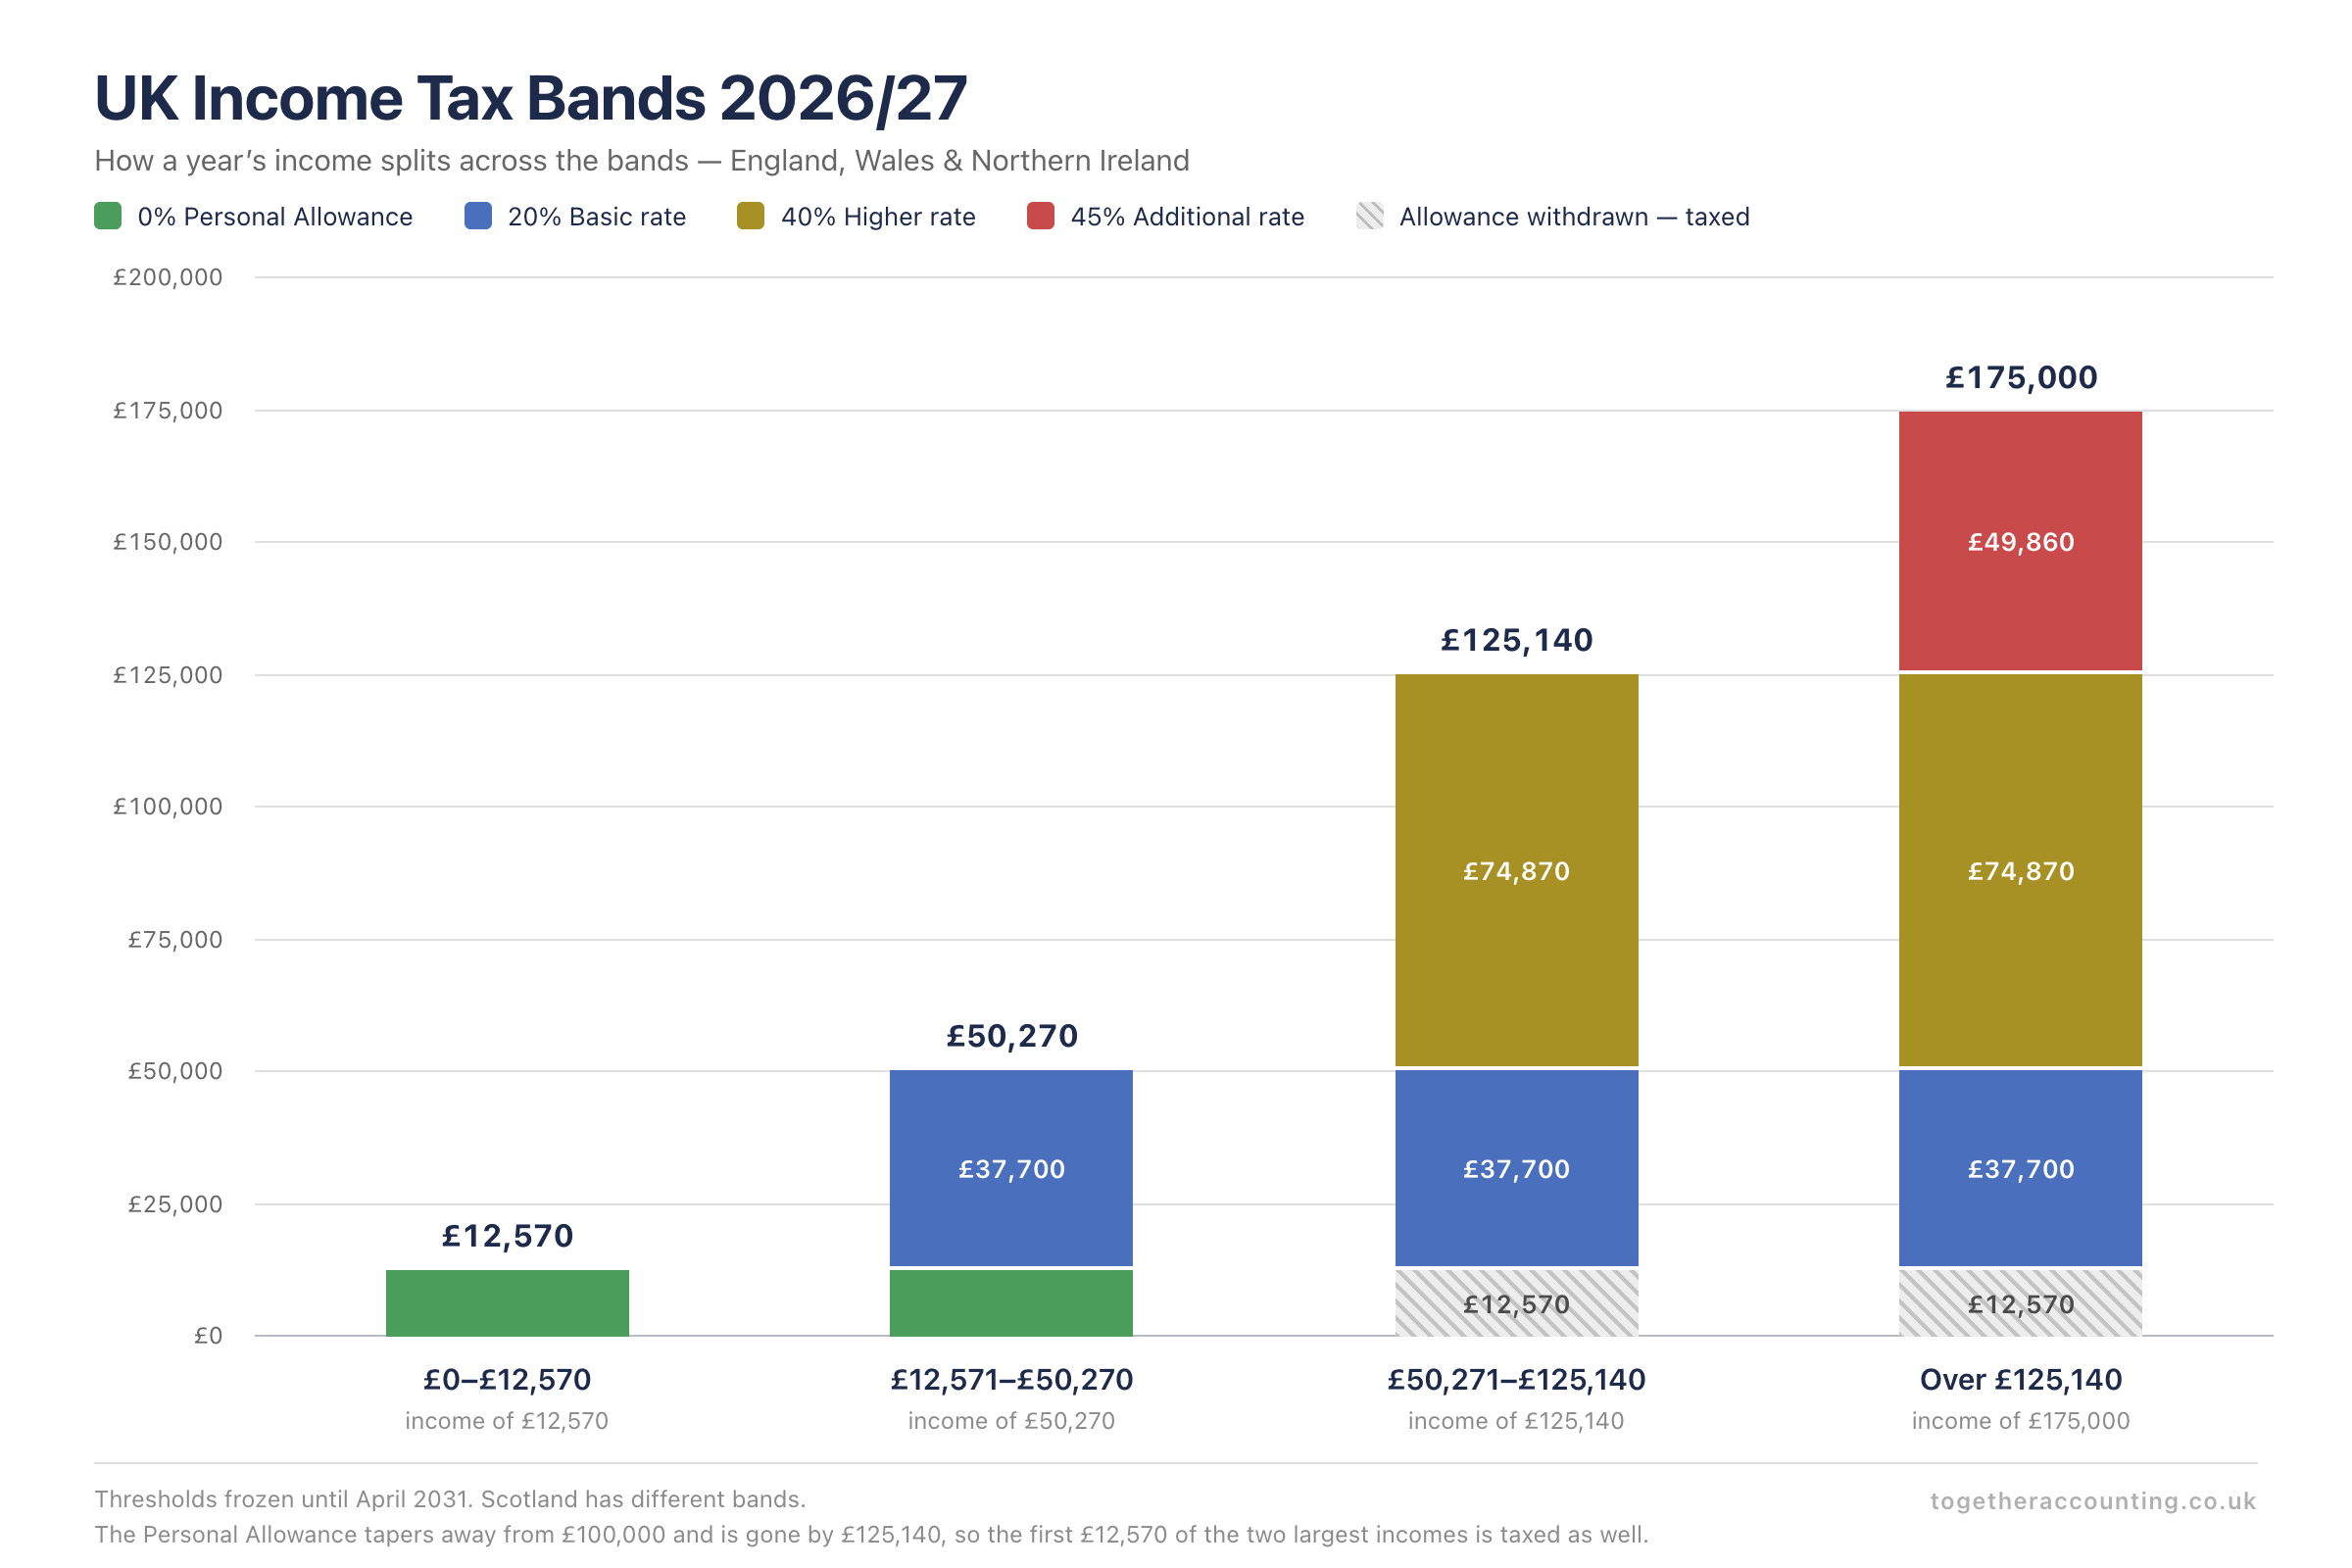
UK income tax brackets 2026/27 (England, Wales and Northern Ireland)
| Band | Taxable income | Rate |
|---|---|---|
| Personal Allowance | Up to £12,570 | 0% |
| Basic rate | £12,571 to £50,270 | 20% |
| Higher rate | £50,271 to £125,140 | 40% |
| Additional rate | Over £125,140 | 45% |
One catch sits outside that table. Once your adjusted net income (your total taxable income before the Personal Allowance, less certain reliefs such as grossed-up Gift Aid donations and pension contributions that get tax relief) passes £100,000, your tax-free Personal Allowance drops by £1 for every £2 you earn above it, and it’s gone entirely by £125,140.
These income tax rates apply to the income you earn. Gains and gifts run on their own tax rates and allowances, so the table above tells you nothing useful about selling a second property.
How UK tax brackets work on your taxable income
Here’s the misunderstanding we correct most often. You start paying income tax once your income passes £12,570, but crossing into the higher rate doesn’t mean you pay 40% on everything. You only pay tax at 40% on the slice above £50,270, and everything underneath keeps the rate it always had. Tax in the United Kingdom is marginal, band by band, which is why a pay rise never leaves you worse off.
Worked Example: Take an employee on a £55,000 salary in 2026/27, standard tax code, paying England, Wales and Northern Ireland rates, with no pension contributions and no student loan.
- Personal Allowance: £12,570 at 0%
- Basic rate: £37,700 at 20% = £7,540
- Higher rate: £4,730 at 40% = £1,892
- Income tax total: £9,432
- Employee National Insurance: £37,700 at 8% (£3,016) plus £4,730 at 2% (£94.60) = £3,110.60
- Total income tax and NI: £12,542.60
Repaying a Plan 2 student loan? Take off another 9% of everything above £29,385, which is £2,305.35 a year at this salary, and a postgraduate loan takes 6% of everything above £21,000 on top of that.
Where a £55,000 salary goes in 2026/27
| Take-home 77.2% |
Income tax £9,432.00 |
National Insurance £3,110.60 |
Take-home pay £42,457.40 |
Based on a £55,000 salary, standard tax code, no student loan or pension contributions, 2026/27 rates. Gross salary £55,000 = income tax £9,432.00 + employee NI £3,110.60 + take-home £42,457.40. Source: Together Accounting worked example.
So is it better to earn £50k or £55k? Always £55k. Only £4,730 of that extra money touches the 40% band, and after tax and National Insurance contributions the £55,000 earner still takes home thousands more. The 40% rate stings, but it never eats the whole rise.
The Personal Allowance and the £100,000 trap: how 40% becomes 60%
This is the one that genuinely costs people, and almost nobody sees it on their payslip. Between £100,000 and £125,140, every extra £2 of income strips away £1 of Personal Allowance. You pay 40% on the new money, plus additional tax on the allowance you just lost, which works out at an effective tax rate of 60% across that band.
Your marginal tax rate as income rises (England, Wales & NI, 2026/27)
| Personal Allowance £0 to £12,570 |
|
||
| Basic rate £12,571 to £50,270 |
|
||
| Higher rate £50,271 to £100,000 |
|
||
| The 60% trap £100,000 to £125,140 |
|
||
| Additional rate Over £125,140 |
|
The 60% band isn’t a real tax rate. It’s the 40% higher rate plus an effective extra 20% from losing £1 of Personal Allowance for every £2 earned above £100,000. These are income tax rates only. Employee National Insurance of 2% on earnings above £50,270 comes on top. Source: gov.uk Income Tax rates and Personal Allowances, and Together Accounting calculations.
Consider a director drawing a £110,000 salary. The taper cuts their Personal Allowance from £12,570 down to £7,570, pushing taxable income up to £102,430. Income tax lands at £33,432, employee NI adds £4,210.60, and the combined bill is £37,642.60. That assumes England, Wales and Northern Ireland rates, a standard tax code and no pension contributions, and any student loan repayments would come on top.
The standard fix is a pension contribution large enough to bring adjusted net income back to £100,000 or below. Do that and the full allowance comes back, so £10,000 into a pension can cost around £4,000 net. Keep the pension annual allowance in view while you plan, because paying in more than the annual allowance (£60,000 this tax year, with a possible three-year carry forward and a taper for very high earners) can trigger a tax charge on the excess. If you’re anywhere near six figures, this is the single highest-value conversation you can have before 5 April.
Dividends, savings and tax-free allowances in 2026/27
Tax on dividend income went up on 6 April 2026. The ordinary rate is now 10.75%, the upper rate 35.75%, and the additional rate stays at 39.35%. The first two both rose by two percentage points, and the dividend allowance sits at a thin £500.
Dividend tax rate changes from 6 April 2026
| Ordinary (basic) rate |
2024/25 8.75% |
→ |
2026/27 10.75% |
| Upper (higher) rate |
2024/25 33.75% |
→ |
2026/27 35.75% |
| Additional rate |
2024/25 39.35% |
= |
2026/27 39.35% |
The dividend allowance stays at £500. The additional rate is unchanged. The ordinary and upper rates both rose by 2 percentage points on 6 April 2026. Source: gov.uk Tax on dividends.
Let me be blunt about what that means for company directors: the old reflex of low salary, high dividends is worth less than it was. Whether it still wins depends on your figures, and the April 2026 dividend rise has narrowed the gap, so check them, and if you haven’t re-run your split since April you’re working off stale maths. The Budget also confirmed that the way company distributions are taxed will be reformed from April 2028, with draft legislation due in 2027, so it’s worth keeping the plan under review.
Scottish income tax rates and bands 2026/27
Scotland sets its own rates on earned income, and there are six bands rather than four.
| Band | Taxable income | Rate |
|---|---|---|
| Starter | £12,571 to £16,537 | 19% |
| Basic | £16,538 to £29,526 | 20% |
| Intermediate | £29,527 to £43,662 | 21% |
| Higher | £43,663 to £75,000 | 42% |
| Advanced | £75,001 to £125,140 | 45% |
| Top | Over £125,140 | 48% |
The Personal Allowance and its £100,000 taper still apply, because HM Revenue and Customs (HMRC) sets those UK-wide. The pinch point is the Higher band starting at £43,663, roughly £6,600 earlier than in England. Wales sets a Welsh rate of income tax but has again left it matching England and Northern Ireland, so Welsh taxpayers use the first table.
National Insurance contributions on top of the income tax thresholds
Employees pay 8% on earnings between £12,570 and £50,270, then 2% on everything above. Those tax thresholds are frozen alongside the income tax bands, so the same drift applies.
Self-employed people pay Class 4 at 6% on profits between £12,570 and £50,270 and 2% above that. Class 2 is treated as paid once profits pass the £7,105 Small Profits Threshold, and below that you can pay voluntarily at £3.65 a week to protect your state pension record.
Employers pay 15% on everything above a £5,000 Secondary Threshold. The Employment Allowance is £10,500, which wipes out a decent chunk of that on a smaller payroll, but you have to claim it and you can’t if you’re a sole director with no other employees. For a full breakdown of what an employee actually costs once NI, pension contributions and on-costs are added in, see the true cost of employing someone in 2026-27.
What changed since 2024/25: income tax rates, thresholds and what’s coming
| Change | 2024/25 | Now or confirmed | Effective |
|---|---|---|---|
| Dividend ordinary rate | 8.75% | 10.75% | 6 April 2026 |
| Dividend upper rate | 33.75% | 35.75% | 6 April 2026 |
| Employer NI rate | 13.8% | 15% | 6 April 2025 |
| Employer Secondary Threshold | £9,100 | £5,000 | 6 April 2025 |
| Employment Allowance | £5,000 | £10,500 | 6 April 2025 |
| Threshold freeze runs to | April 2028 | April 2031 | Autumn Budget 2025 |
| Scottish starter and basic bands | Narrower | Widened | 6 April 2026 |
| Savings income rates | 20/40/45% | 24/44/49% | 6 April 2027 |
| Property income rates (England, Wales and NI) | Taxed as other income | 24/44/49% | 6 April 2027 |
The property and savings lines are the ones landlords and investors should be circling. The final rates for both were set at Budget 2026, with legislation to follow in Finance Bill 2026-27, and both start on 6 April 2027. Each rate rises by four points in total (basic 20% to 24%, higher 40% to 44%, additional 45% to 49%): two announced at Budget 2025 and a further two at Budget 2026. That lands on income many people still treat as passive.
As for the freeze to April 2031, its effect builds quietly. The freeze comes with no rise in the headline earnings rates, but as pay rises more people are pulled into higher rates while the bands stay fixed.
Fiscal drag: frozen bands pull more people into higher rates as pay rises
|
£12,570 |
£37,700 |
|
£50,270 |
Frozen to April 2031 |
Capital gains tax and inheritance tax sit outside these bands
Two big taxes ignore the table above. Capital gains tax has its own rates and its own tax-free allowance, and inheritance tax runs on separate thresholds again. Your income tax bands still matter for gains: whether a gain is taxed at the lower or the higher rate depends on how much basic-rate band your income leaves spare. Inheritance tax pays no attention to your bands at all. We cover both elsewhere on the site.
What to do about it: pensions, Marriage Allowance and timing
Knowing your UK tax bracket shapes every decision below, and each of these trims your annual income tax bill in a different way.
-
Re-run your salary and dividend split. The two-point rise in the ordinary and upper dividend rates that took effect in April 2026 changes the arithmetic for every owner-managed company. Do it early in the tax year rather than patching it in March. -
Use pension contributions to clear £100,000. If your adjusted net income lands between £100,000 and £125,140, a contribution that pulls you back to £100,000 or below restores your Personal Allowance at an effective 60% relief. It’s the cleanest saving in the whole tax code. -
Claim the Marriage Allowance if you qualify. Where one partner earns under £12,570 and the other is a basic-rate taxpayer, you can transfer £1,260 of allowance and save up to £252 a year. Claims can be backdated, so it’s often worth more than one year’s figure suggests. Don’t mix it up with the Married Couple’s Allowance, which is a separate and much older relief that only applies where one of you was born before 6 April 1935. -
Check who holds the income-producing assets. Shifting savings or dividend-paying shares to a lower-earning spouse uses their Personal Allowance, basic-rate band and £500 dividend allowance. Done properly, the income belongs to them for tax purposes and it’s perfectly legitimate. -
Look at the starting rate for savings. With low non-savings income, up to £5,000 of interest can be tax-free on top of your allowance. Couples with uneven incomes should review where the savings actually sit. -
Plan around 6 April 2027 now. Property and savings rates rise that day (both to 24/44/49%), so anything you can sensibly bring forward has about five months’ runway. Rushed decisions in March 2027 tend to be expensive ones.
FAQ
How much can I earn before I pay 40% tax in the UK?
In England, Wales and Northern Ireland you start paying 40% on income above £50,270, once your £12,570 Personal Allowance and the £37,700 basic rate band are used up. In Scotland the Higher rate of 42% begins at £43,663. Only the income above the threshold is taxed at the higher rate, not the whole lot.
What is the 60% tax trap?
It’s the band between £100,000 and £125,140, where your Personal Allowance is withdrawn at £1 for every £2 of income. You pay 40% on the extra earnings, plus an effective extra 20% because every £1 earned removes 50p of allowance that would have been taxed at 40%, giving an effective marginal rate of 60%. Nothing on your payslip says so, which is why so many people miss it.
How can I avoid 40% tax legitimately?
Pension contributions reduce your adjusted net income and are the most effective option for most people. Salary sacrifice works in a similar way and cuts National Insurance too, although from April 2029 only the first £2,000 a year of salary sacrificed pension contributions will stay free of National Insurance. Marriage Allowance helps couples with uneven incomes, and timing a bonus or dividend across two tax years can keep you under the threshold in either one.
What income tax band am I in?
Add up all your taxable income for the year, take off your personal tax allowance, and see which band the remainder falls into. That’s your UK tax bracket. Your tax code is a decent clue but not proof, because it may not reflect dividends or rental profits, which often have to be reported on a self-assessment tax return. HMRC may adjust your code for untaxed savings interest. Where several income sources are in play, check it properly.
When does the UK tax year run?
From 6 April to 5 April the following year. The 2026/27 tax year started on 6 April 2026 and ends on 5 April 2027, and that’s the period all the rates and allowances above apply to.
If you’re in Norwich or anywhere else in Norfolk and you’d rather someone ran your numbers properly than guess from a table, get in touch. A half-hour conversation usually pays for itself.
This article gives general guidance based on current legislation. Please take advice on your own circumstances before acting on it.
